Scaling for the Future: ProVise Announces Move to New Clearwater Headquarters
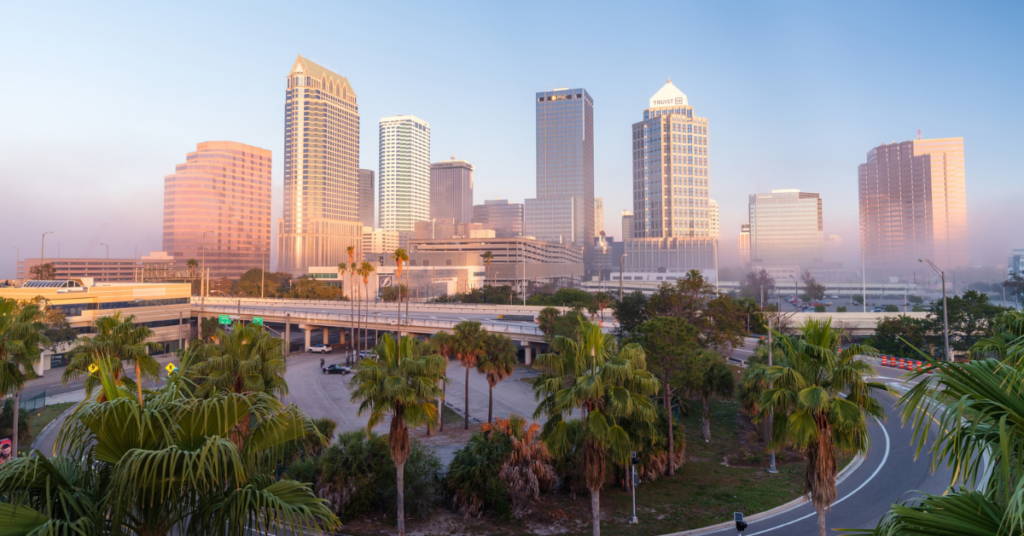
ProVise Management Group announces plans to relocate its Clearwater headquarters to a new 10,584-square-foot office at 300 Park Place Blvd., Suite 200A, Clearwater, FL 33759, with occupancy expected in mid-August.
The move comes as ProVise approaches its 40th anniversary on August 22 and reflects the firm’s continued growth. Founded in 1986 by V. Raymond Ferrara, CFP®, ProVise serves more than 1,100 clients in over 30 states and manages approximately $2 billion in assets. The firm’s expanding team and client base made a larger, more centrally located headquarters a natural next step.
“After more than 30 years on Druid Road, it is time to make a move,” said Ferrara. “We have simply outgrown the space, and as our business continues to grow, a more central location in Pinellas County makes sense for both our clients and our team.”
The new office was designed to support future growth while enhancing collaboration among team members and providing an improved experience for clients. Located in the heart of Pinellas County, the headquarters offers convenient access for clients throughout the Tampa Bay region. The firm will also retain their Tampa location, now offering utmost flexibility with these two office locations.
“This move is really the result of 40 years of steady, intentional growth,” said Jon Brethauer, President of ProVise. He hopes the new space “sends a message of confidence and commitment. ProVise has always taken a long-term view, not only when developing financial plans, but also in how we’ve built our firm. We’re not changing who we are. We’re simply creating an environment that allows us to continue delivering the thoughtful, personal advice our clients have come to expect while preparing for the opportunities ahead.”
“For all of us who have worked here over the years, our office has been more than just a workplace — it’s been our home,” said Eric R. Ebbert, CFP®, CEO of ProVise. “While it is difficult to leave a space that has been such an important part of our history, this move is an exciting next step. Our new headquarters gives us room to grow, strengthens our ability to serve clients throughout the county, and positions us well for the future while preserving the values and personalized service that have always defined ProVise.”
The relocation coincides with a period of sustained growth for the firm and marks the beginning of its next chapter. While the address is changing, ProVise’s commitment to fiduciary advice, client service, and community involvement throughout Tampa Bay remains unchanged.
Best Stock Market Performance Since 2020 in 2nd Quarter
While the results from the 1st quarter were muted in large measure because of the Iran War, the second quarter rewarded investors’ patience. The Dow Jones Industrial Average total return was up 13.38% during the quarter, while the total return of the S&P 500 and MSCI EAFE index was up 15.20% and 11.08%, respectively. Neither the war, nor anything else seems to have dampened investors’ enthusiasm. As the old Wall Street saying goes, “the market climbs a wall of worry” in these turbulent times. Much of this has been powered by the AI trade which some believe may be slowing down, so don’t be surprised if a pullback occurs over the next few months. That said it will be earnings that will push the market higher. Hype only goes so far with investors.
What is the Best Long-Term Investment?
You may be surprised by the answer from two recent polls and to no surprise it also depends on when the question is asked. Even though the S&P 500 has produced an average annualized return of 11.5% according to Fidelity, it was only picked by 20% of those polled. At the top of the list is real estate, selected by 38% of respondents, followed by gold at 18%, saving accounts and certificates of deposit by 12%, and bonds by 4% with a bewildering 2% thinking that crypto was the best.
Gallup has done a similar poll in the past. During the 2008 Great Recession, savings accounts/certificates of deposit won the day. In 2011 and 2012, it was gold that was #1. That is really strange because gold’s spot price was about $1,414 on 1/1/2011, climbed to $1,900 in September and finished the year at $1,333. So, gold was actually down for the year while the S&P 500 was up about 1%. Gold rose about 7% in 2012, while the S&P 500 was up about 13.3%.
In reality, the “best” long-term investment is often reflective of the economy at the time (short-term bias) and in the eye of the beholder. For us, the “best” investment is defined as a well-diversified portfolio that lines up with your financial goals and matches your risk tolerance level. Different strokes for different folks.
Fixing Social Security
We have written many times about the Social Security Trust Fund running out of money by 2032. As a result, there will only be enough money to cover about 78% of the benefits that are owed. Congress knows this issue well and has kicked the can down the road for over a decade. There is no easy fix.
According to The Kiplinger Letter raising the maximum amount of income that is taxed from the current $184,000 to $330,000 only solves about 26% of the problem. But what if you taxed all wages with no limit? The Social Security Administration says it would cover about 43% of the gap over the next 75 years if the current benefit formula were to continue and perhaps up to 78% if there is an adjustment to the formula that would be to the detriment of high wage earners. Hiking the tax by 1% for everyone could potentially close another 26%.
There you go, now we have it covered and a little extra for the future. But hold on. Eliminating the cap on income would raise about $3.4 trillion over the next 10 years and the 1% hike (0.5% to the employee and employer) would raise about $800 million. In short, these would create the biggest tax hike in history. That means less money for consumers to spend and less profits for corporations which would likely lead to layoffs and lower stock prices. No matter the “fixes” there will be plenty of pain for everyone to share.
Concerned About Retirement
According to the Employee Retirement Research Institute, more Americans than ever are concerned about not having enough saved for retirement in spite of people saving more and a strong stock market over the past decade. Thirty-nine percent of employees and 27% of retirees think they’ll run out of money. This big drop from previous years is most likely reflected in the concerns about inflation.
Many people are going to work much longer than they want to overcome this fear, and some may have to work well into what would be a normal retirement age. Well, that may be a good plan. The reality is that some could be laid off if the economy turns down, develop health issues or care for parents or a spouse. Unfortunately, 40% of those interviewed have $25,000 or more in debt not including their mortgage. Needless to say, thinking about the security or lack of Social Security carries a heavy weight.
Paycheck-To-Paycheck
Ever heard of Solo Funds, a fintech company that lets you lend, borrow and bank with other members on your terms. Neither did we until they recently released a survey of 2,000 people called Cash Poor Report. It found that 44% called themselves “cash poor” which meant they had less than $200 in savings and 70% said they were “financially stressed” with about 40% still employed. This paycheck-to-paycheck phenomena is creeping up the income stream to even hit some in the six-figure bracket. All of this leads to food insecurity, more borrowing than healthy and forcing families to make very difficult choices.
Millennials Want Family Meetings
Nationwide Retirement Institute recently released the Advisor Authority study which indicates that 6 in 10 millennials want to have family meetings with their parents and grandparents, and they are asking their financial advisor to facilitate these meetings. But there is a generational gap that exists as only 24% of Baby Boomers have actually sat down to share and even when they share it can be at substantially different levels of detail. To start, 27% of Baby Boomers don’t see any need to have a family meeting. They simply don’t think there is a need until there is a need – like should they be hit with an illness. To these Boomers we suggest that they at least have a conversation to lay out their personal and financial plan should they have mental or physical issues that would necessitate them having assistance.
This can cause great anxiety on both sides. The children want to understand how it might affect their financial planning, and the parents think it is none of their business. At the other end of the spectrum, about a quarter of Baby Boomers are sharing information about their wealth and what their intentions are regarding this wealth. Explaining about charitable contributions at death, why one child was chosen to settle the estate, why a trust company was used to keep the money in trust, what gifting the parents are willing to do during life, letting the children know about life insurance, talking about long-term care, end of life planning, and much more can often be expressed in advance. If you have a desire to have us facilitate a family meeting, let’s spend some time talking about the pros and cons.
Trump Accounts are Live
On July 4th, almost six million “Trump” accounts were opened on-line at www.trumpaccounts.gov. These accounts were created by the One Big Beautiful Bill Act last year and they allow any child under the age of 18 to participate. Once set up, parents, grandparents, and even employers can make contributions that total no more than $5,000 per year. A company can contribute up to $2,500 to employees on a non-discriminatory basis and it is tax deductible to the company, tax free to the employee, and neither pay any payroll taxes. For children born January 1, 2025 through December 31, 2028, the government will seed the account with $1,000. When the child turns 18, the Trump Account turns into a regular IRA.
School Is Out, Planning Is In
Summer is in full swing, meaning thousands of prospective college students are visiting campuses across the country. College remains, statistically, one of the most effective paths to higher lifetime earnings. However, the supply of higher education in the United States has begun to outpace demand. As a result, many colleges and universities have increased their scholarship and financial aid offerings, creating valuable opportunities for families to help offset the rising cost of higher education. If the current trend of declining birth rates continues, this imbalance could eventually lead to the closure of some institutions.
Several universities across the country stand out for providing generous merit-based financial aid. Schools such as Principia College and Trinity University rank among the top 100 liberal arts institutions in the nation while offering substantial merit-based scholarships to prospective students. Others, including Asbury University and Florida Southern College, rank highly within their respective regions and provide significant scholarship opportunities as well.
Here in Florida, the Florida Prepaid College Plan is a program that allows families to lock in tuition costs at today’s rates. The plan can even be applied to most accredited private and out-of-state colleges and universities nationwide. So, while college costs have not declined thus far, more schools will have to provide assistance to stay afloat over the long term.
Charitable Giving on the Rise
Markets have performed well over the past few years, increasing opportunities for individuals and families to leave a meaningful legacy to surviving family members and charities. In 2025, U.S. charitable giving increased by an inflation-adjusted 3%, to $617 billion. Who are the biggest contributors to charitable giving? Bequests left through wills, which rose 16.6% to $62 billion.1
For charitably inclined clients, strategies such as gifting cash, donating appreciated securities, using a donor-advised fund, or creating a private foundation may support important causes while aligning with broader tax, estate, and financial planning goals. At ProVise, we support starting the conversation early to help ensure our clients’ generosity is carried out thoughtfully and according to their wishes.
_______________________________________
1Giving USA 2026: The Annual Report on Philanthropy for the Year 2025, a publication of Giving USA Foundation, 2026, researched and written by the Indiana University Lilly Family School of Philanthropy
Up Your Assets™
Episode 35: How to Avoid Financial Devastation When Life Happens

Life in the big leagues is where you want to play; however, there can be some big curve balls thrown your way! A strikeout would be devastating, so be prepared to knock it out of the park and have your money plan ready to keep up! In this episode, financial expert Eustache Clerveaux, CFP®, CPWA®, EA, CDFA®, shares insights with your host Ray Ferrara, CFP® on how to prepare financially for life’s major transitions, unexpected events, and windfalls. Learn practical strategies to build and maintain effective cushions within your financial plan and win the financial series. Batter Up!
Acknowledgements and Important Disclosures
From the Up Your Assets website
Apple
Spotify
YouTube